Yue Cao, a former bank analyst, was sentenced to 10 years after a jury convicted him on 15 federal counts for a scheme that prosecutors say created unauthorized online banking access for elderly customers and diverted about $2 million. The fraud was uncovered after a $50,000 unauthorized transfer triggered a bank’s monitoring system, sparking internal reviews and an FBI probe. Two indictment counts were later dismissed after a victim recanted an earlier claim, but the court found the remaining evidence sufficient for conviction. Regulators urge customers to monitor statements and watch for signs of identity theft.
Ex-Bank Analyst Sentenced to 10 Years After Scheme That Diverted About $2 Million From Elderly Customers
Image Credit: Shutterstock.
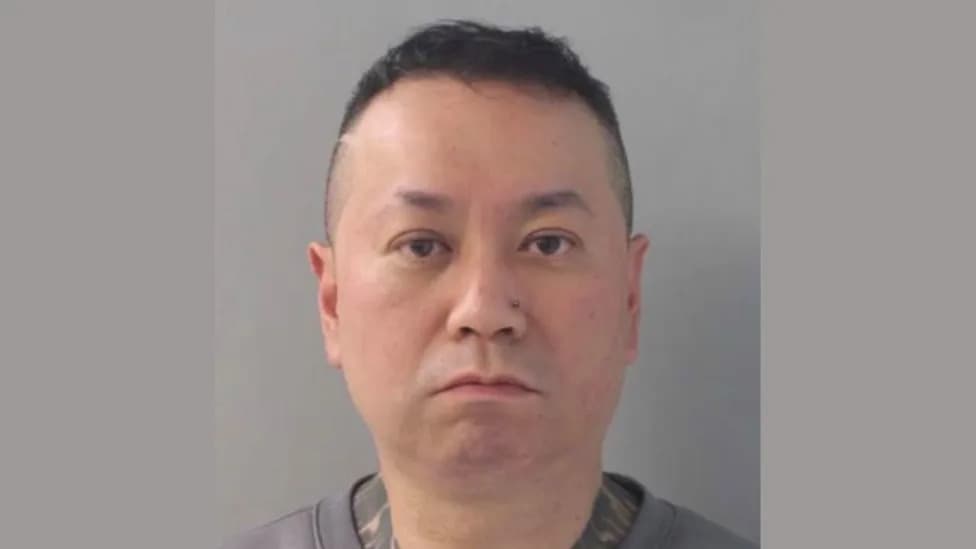
A former bank analyst, Yue Cao, 36, was sentenced to 10 years in federal prison after a jury convicted him of bank fraud, aggravated identity theft and money laundering in a scheme prosecutors say created unauthorized online access for elderly account holders and moved roughly $2 million.
Overview
U.S. District Judge J. Philip Calabrese imposed a 120-month prison term and five years of supervised release, according to the U.S. Attorney's Office for the Northern District of Ohio. Cao was convicted in February on 10 counts of bank fraud, four counts of aggravated identity theft and one count of money laundering.
Alleged Scheme
Prosecutors say Cao targeted particularly vulnerable customers — account holders ages 90 to 103 across New York, Pennsylvania, Connecticut, Washington and Ohio — who had not enrolled in online banking. According to the government, he used an offshore service to create email accounts in the names of more than 100 customers, enrolled those customers in online banking without authorization, and redirected account notices and statements to email addresses he controlled.
Authorities allege Cao then moved funds from legitimate customer accounts into additional bank and brokerage accounts he controlled or used, and that some of the money was used for options trading that, in some instances, involved his personal brokerage account.
Investigation And Trial
The scheme began to unravel in April 2023, when a second financial institution detected an unauthorized $50,000 transfer from a Cleveland bank customer into Cao’s checking account. Internal reviews and cross-institution communication led to an FBI investigation.
Cao had worked from 2015 until June 2022 as a quantitative modeling analyst at a federally insured Cleveland-based financial institution, a role that gave him access to extensive customer and account data. After that employment, a different institution in Westlake, Texas, hired him to develop models to predict and monitor fraud.
Cao was originally indicted in May 2024 on 17 federal counts. After one elderly customer later told investigators he had authorized a $100,000 transfer that prosecutors had initially treated as unauthorized, the government asked the court to dismiss the related counts; Judge Calabrese dismissed two counts without prejudice in April 2025. The court also addressed limited inaccuracies in how some IP-address evidence and account references were described but found they did not undermine the grand jury’s probable-cause determination.
The case proceeded to trial in February 2026 on the remaining 15 counts. After a five-day trial, a jury convicted Cao on all counts. His sentence was imposed on Sept. 17, and an appeal was filed in the U.S. Court of Appeals for the Sixth Circuit later that month.
Consumer Warnings
Regulators say the case highlights common identity-theft and account-takeover red flags. The Federal Deposit Insurance Corporation (FDIC) advises customers to monitor account statements, contact their bank if an expected statement does not arrive, and enable alerts for account activity. The Federal Trade Commission (FTC) lists unexplained withdrawals, unfamiliar accounts and missing bills as warning signs of identity theft.
Key takeaway: Even customers who do not use online banking can be targeted; consumers should monitor mail, emails and account statements and report suspicious activity promptly.
Help us improve.