The Texas Department of Insurance says insurers cannot deny or decline to renew homeowners policies solely because a home or its systems (roof, wiring, HVAC, plumbing, siding) are old, citing 28 Tex. Admin. Code § 21.1006. Commissioner Amanda Crawford framed the clarification as a fairness and transparency measure for consumers. Gov. Greg Abbott noted average homeowners' premiums in Texas rose 79% over six years. The guidance gives homeowners firmer grounds to contest age-only denials while insurers face broader market pressures nationwide.
Texas: Insurers Can't Deny Home Coverage Solely Because Roofs, Wiring or HVAC Are Old
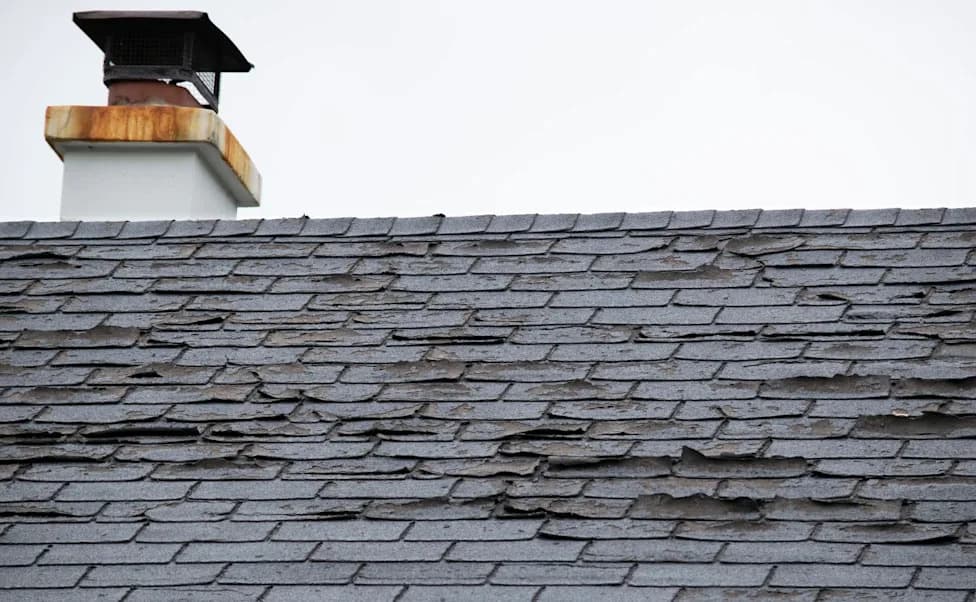
Photo Credit: iStock
Many Texas homeowners worry that insurers can refuse to issue or renew a policy simply because a house—or components such as the roof, electrical wiring, or HVAC—are old. The Texas Department of Insurance (TDI) says they cannot.
What the Rule Requires
TDI clarified that insurers may not deny or decline to renew a residential property insurance policy based solely on the age of the home or the age of specific components. This protection is grounded in 28 Tex. Admin. Code § 21.1006, and TDI emphasizes that age alone should not determine eligibility for coverage.
Which Components Are Covered
- Roofs
- Electrical wiring and systems
- Heating, ventilation and air conditioning (HVAC)
- Plumbing
- Siding and other exterior materials
"Texans deserve fair access to home insurance, no matter the age of their home," Insurance Commissioner Amanda Crawford said. "By strengthening clarity and accountability, we're building a more transparent insurance market that supports Texans."
Context: Rising Premiums and Consumer Protections
The clarification comes amid sharply rising insurance costs across the state. Gov. Greg Abbott cited a 79% increase in the average annual homeowners' insurance premium in Texas over six years. Abbott has directed the Texas Department of Insurance to prioritize consumer protections and actions to help make property and casualty insurance more affordable.
What This Means for Homeowners
Homeowners who receive a denial or nonrenewal that cites only the age of the home or its systems have stronger grounds to question that decision. TDI's guidance signals to insurers that age alone cannot be used as a blanket justification to refuse or drop coverage. Policyholders can and should ask insurers for a specific, documented reason for any adverse action.
Broader Market Trends
Pressure on homeowners' insurance extends beyond this regulation and beyond Texas. Insurers nationwide have tightened underwriting, raised premiums, or declined renewals in some markets. Notable trends include:
- Rising premiums reshaping household budgets and housing decisions in Texas and other states.
- Clusters of nonrenewals in specific markets, such as parts of California.
- Limited renewal options for some condo and HOA residents as carriers change appetite for certain property types.
- Post-storm rate spikes and insurer pullbacks in states like Oklahoma.
Practical Steps
- Ask your insurer for a written explanation if you are denied or nonrenewed and the reason given is age.
- Contact the Texas Department of Insurance for guidance or to file a complaint if you suspect an unlawful age-only denial.
- Shop the market and consider independent agents or state-sponsored resources to compare options.
Commissioner Crawford has provided TDI guidance to the market and reported to the governor on actions taken in response to his directive. While this clarification strengthens consumer protections, homeowners should remain vigilant and seek assistance if they believe their rights under the rule are being violated.
Help us improve.