A Missouri homeowner says Clarks Fork Mutual gave only three weeks' notice that it would not renew their policy and later suggested a negative Google review may have influenced the decision. Reddit users and an underwriter disputed that a review alone would prompt nonrenewal, pointing instead to visible property issues — especially the roof — or broader underwriting changes. The policyholder was told the company may not be subject to Missouri's Department of Commerce & Insurance oversight, prompting calls for greater transparency. Commenters advised getting written reasons and shopping for new coverage immediately.
Missouri Homeowner Says Insurer Cited Google Review in Nonrenewal — Redditors and an Underwriter Doubt It
Photo Credit: iStock
A Missouri homeowner who'd insured the same property for nearly a decade says Clarks Fork Mutual gave them only about three weeks' notice that it would not renew their homeowners policy. The policyholder later said a company representative suggested a negative Google review might have influenced the underwriters' decision.
What the Policyholder Reported
In a Reddit post, the homeowner said they chose Clarks Fork Mutual because it was local, competitively priced and a company they wanted to support. After receiving a nonrenewal notice citing "underwriter guidelines," a follow-up phone call reportedly added that the insured was considered an "undesirable customer" and that "sometimes the underwriters do not like what customers write in Google reviews."
Reactions and Pushback
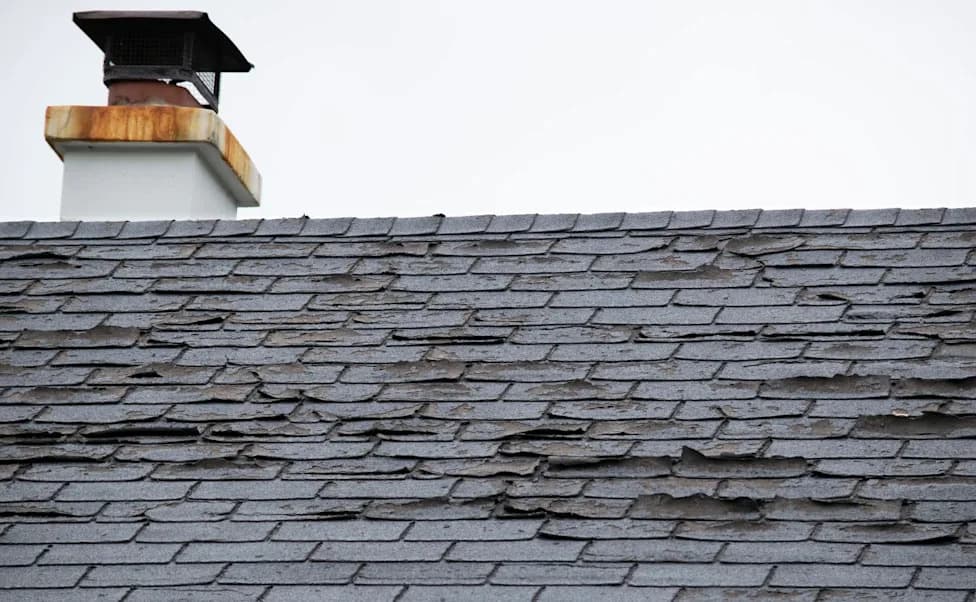
Other Redditors — including one who identified themself as an underwriter — pushed back on the idea that a single negative review would by itself trigger a nonrenewal. Commenters suggested more plausible explanations, such as visible property deterioration (notably the roof) spotted through street-level or satellite imagery like Google Maps or Google Earth.
"As an underwriter, if someone found out that I non-renewed a policy solely because I don't like something the insured said, I'd lose my job," one commenter wrote.
Why Insurers Nonrenew
Nonrenewals are typically tied to underwriting and risk-assessment factors, including but not limited to:
- Visible property condition (aging or damaged roof, structural issues)
- Rising regional risks (flood, wildfire, hail, or crime trends)
- Claims history or suspected fraud
- Changes to a carrier's underwriting guidelines or business strategy
Insurers increasingly use public imagery and third-party data in underwriting. If photos show obvious deterioration, that can inform nonrenewal decisions — but commenters stressed a negative online review alone is an unlikely sole cause.
Regulatory and Practical Concerns
The homeowner said they were told Clarks Fork Mutual does not fall under Missouri's Department of Commerce & Insurance (DCI) oversight and therefore was not subject to the same requirements. That claim raises questions that homeowners should verify: whether the carrier is licensed in the state and what consumer protections apply.
What To Do If You Get a Nonrenewal
- Ask the insurer for a clear, written explanation for the nonrenewal and any supporting documentation.
- Verify whether the company is licensed in your state and, if so, what oversight or appeal rights exist through your state insurance department.
- Begin shopping for replacement coverage immediately and compare policy terms, not just price.
- If you suspect unlawful discrimination or improper reasons for nonrenewal, contact your state insurance regulator for guidance.
Related Reports
Commenters pointed to similar disputes in other states, such as claims that Allstate used Google Earth roof photos when threatening cancellation, a California homeowner suing Liberty Mutual over a contested cancellation, and reports that Lemonade declined to renew policies in high-risk parts of Texas.
Bottom line: While a negative Google review is an alarming thing to hear from a carrier, industry commenters say physical property condition or underwriting changes are more plausible drivers of nonrenewal. Homeowners should seek written reasons and act quickly to secure replacement coverage.
Help us improve.