Homebuyers in California are increasingly pushed into high‑deductible or surplus‑lines home insurance as major carriers retreat amid rising wildfire losses and reinsurance costs. In Menifee, buyer Alex Hwang accepted a surplus‑lines policy with a $25,000 fire deductible after standard insurers refused lender‑required coverage. FAIR Plan enrollment surged in many low‑risk ZIP codes, and surplus‑lines market share rose from about 1% to 7% since 2021, leaving homeowners with fewer options and higher out‑of‑pocket exposure.
California Buyer Pushed Onto 'No‑Name' Policy With $25,000 Fire Deductible as Insurers Retreat
Photo Credit: iStock
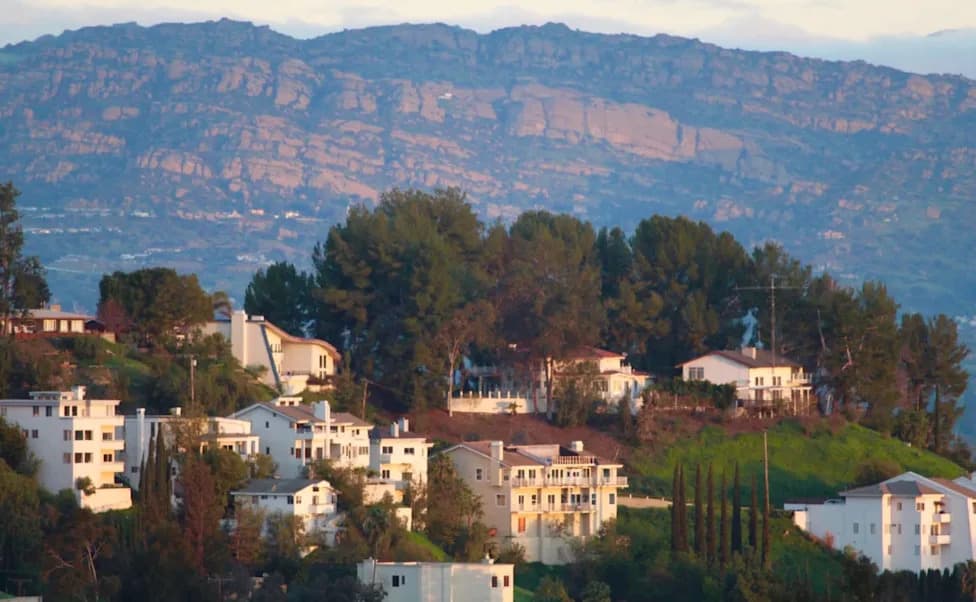
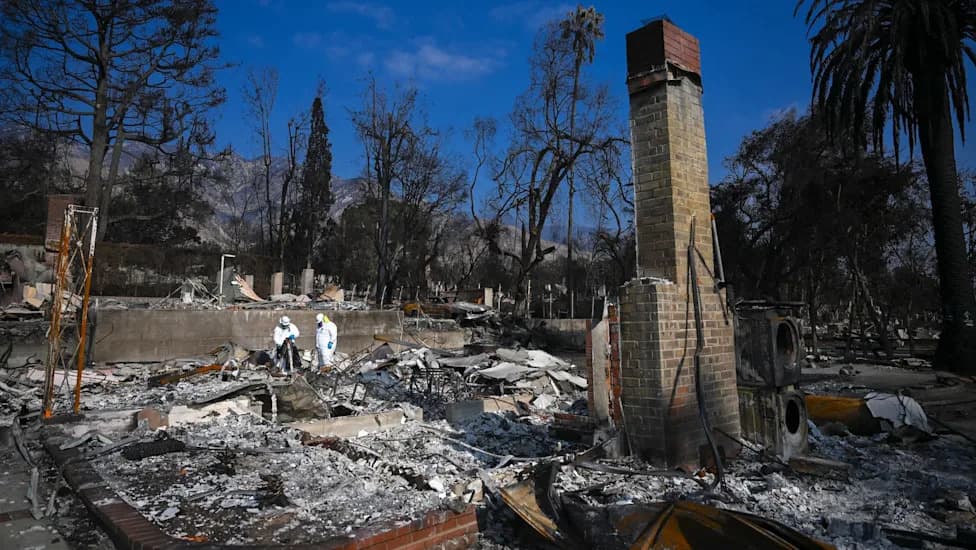
A California homebuyer who expected a routine suburban closing instead found himself forced onto a little‑known surplus‑lines policy that carries a $25,000 deductible for fire losses. His experience highlights how an increasingly strained insurance market has moved beyond high‑risk mountain and forested areas and is affecting more typical neighborhoods.
The case: Tech worker Alex Hwang was buying a nearly $700,000, six‑bedroom home in Menifee’s Cimarron Ridge development when he discovered no standard insurer would provide the lender‑required coverage. With few options, he accepted a surplus‑lines policy that imposes a $25,000 fire deductible. Hwang told the Los Angeles Times he felt "boxed in by the market" and called the carrier "no‑name insurance" because he had never heard of it.
Why this matters: Surplus‑lines insurers operate under different regulations than standard carriers and often carry higher deductibles or unfamiliar underwriting terms. Homeowners who cannot find private coverage can turn to the California FAIR Plan, the insurer of last resort, but it typically covers only fire—leaving owners to buy separate policies for theft, water damage and other perils.
A Los Angeles Times review across 396 ZIP codes found that low‑risk homes accounted for 90% of the policies added to the FAIR Plan between March 2025 and June 2026—more than 11,000 additional low‑risk properties added to a pool that already covered roughly 138,000 similar homes. Around Menifee, FAIR Plan enrollment rose fivefold from 2024 levels, while nearby Hemet saw a 660% increase.
Other buyers in Riverside County have faced similar problems. One purchaser identified only as Louis and his wife purchased a policy that carried a $14,000 fire deductible after conventional carriers declined to insure them.
Insurer pullbacks in California stem from large wildfire losses since 2015, rising construction and rebuilding costs, and pricier reinsurance. As major carriers shrink their exposure, surplus‑lines insurers have expanded—growing from about 1% of the state’s home‑insurance market in 2021 to roughly 7%, according to Weiss Ratings—leaving more homeowners with higher out‑of‑pocket risk and unfamiliar providers.
State Response and Wider Impact
The California Department of Insurance has pointed to the scale of catastrophic fires and climate‑related risk increases as major strains on the market. State reforms aim to encourage insurers to write more policies in wildfire‑impacted areas while allowing companies to factor catastrophe models and reinsurance costs into underwriting decisions.
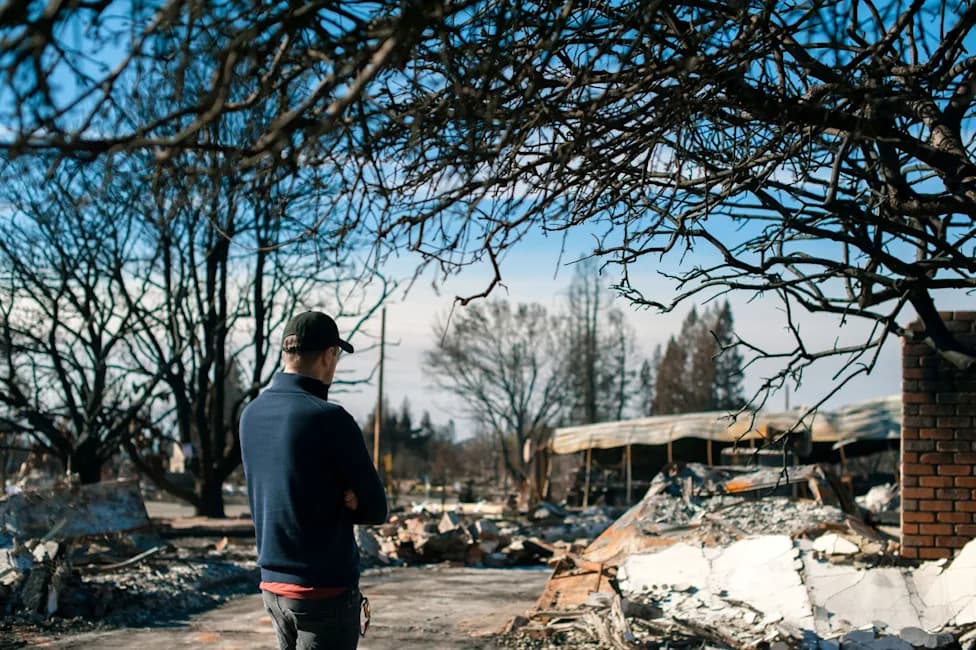
Examples of the fallout across the West include homeowners dropped in Los Angeles before the Palisades Fire, a major carrier that stopped issuing new homeowner policies in California, abrupt carrier pullbacks in Nevada, and lawmakers in New Mexico warning that catastrophic fires are reshaping homeownership prospects.
Bottom line: As standard insurers continue to retreat from parts of California, more buyers may face higher deductibles, limited coverage options, or reliance on the FAIR Plan or surplus‑lines carriers—making homeownership riskier and more costly for many families.
Help us improve.