Long-term care costs for nursing homes, assisted living, and home care have surged for decades, forcing many families to use savings, home equity, or leave jobs to provide care. Key drivers include rising caregiver wages, higher insurance and service costs, workforce shortages, and demographic shifts that increase demand. Policymakers and some states are testing fixes — from payroll-funded programs like WA Cares to federal proposals for long-term care trust funds — but significant reform and investment in the workforce and housing are needed to protect future retirees.
Long-Term Care Costs Are Soaring — How Families Are Paying the Price
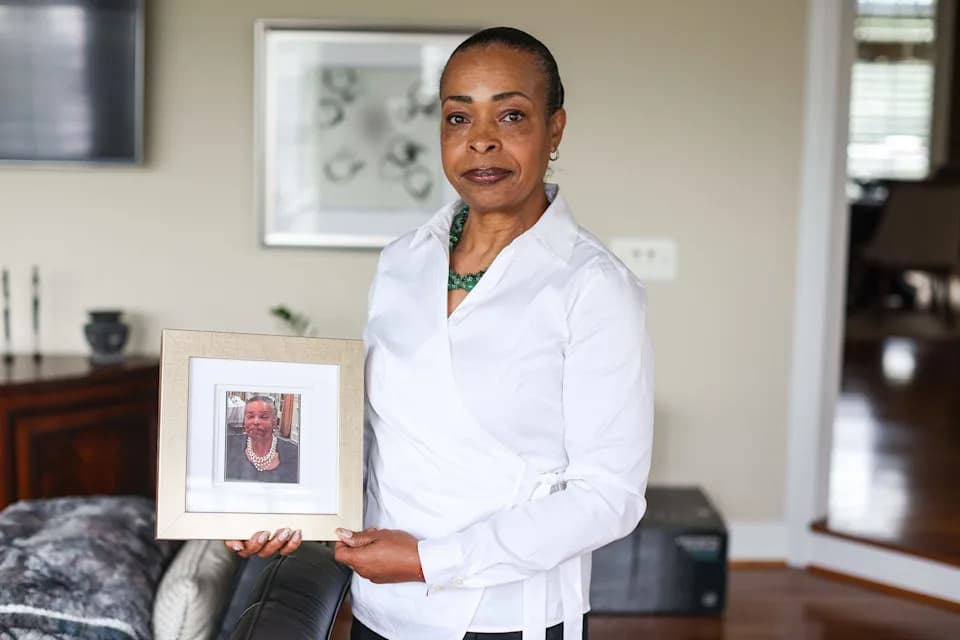
Tamara Johnson holds a framed photo of her mother.Valerie Plesch for BI
Some days Tamara Johnson still wonders how her life shifted so quickly. At 58, Johnson had been earning six figures in an executive role when her mother’s 2017 Parkinson’s and dementia diagnosis prompted a move from New Orleans to Virginia so she could care for her while continuing to work. After her mother died in 2020, Johnson’s husband suffered a series of catastrophic medical events that required full-time care. She took leave and ultimately quit this year, drawing on a deferred-resignation program and personal savings. She estimates the family spent more than $700,000 caring for her mother and husband combined.
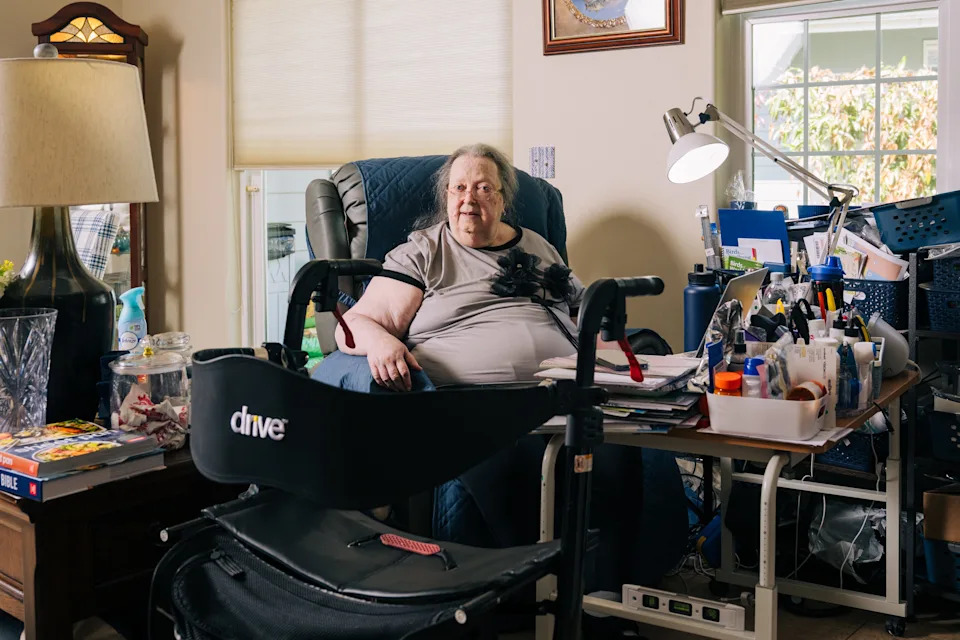
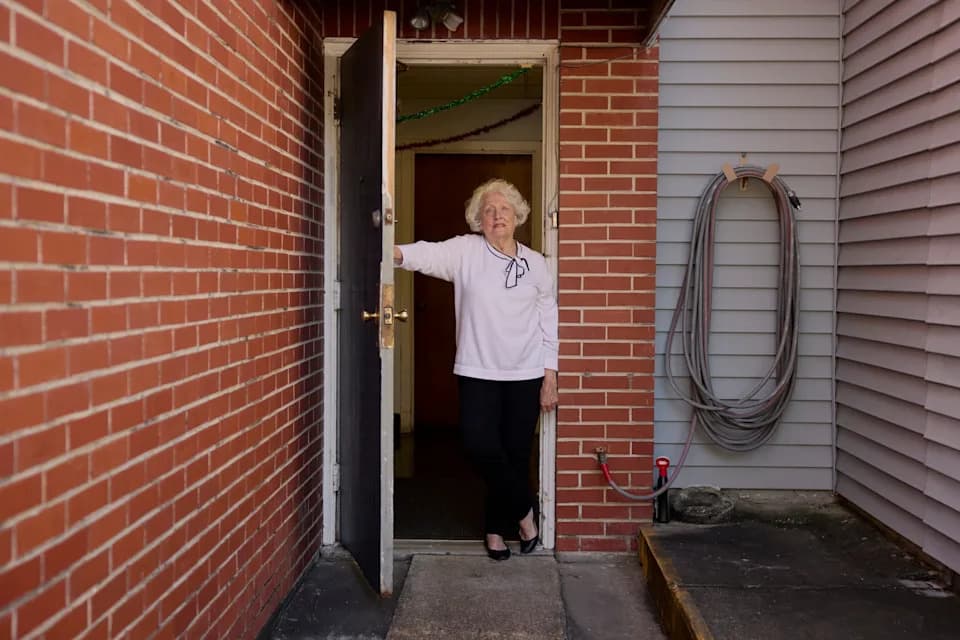
Lana Mountford lives in a development for people aged 55 and older.Chona Kasinger for BI
Families Face Growing Financial Strain
Johnson’s story is not unique. Eldercare costs — from nursing homes and assisted living to home health aides and adult day services — have risen faster than overall consumer prices for decades. Many families report six-figure bills, tapping home equity, retirement savings, loans, and in some cases leaving jobs to provide unpaid care themselves. For those with limited savings, long-term care costs can quickly erode financial security and jeopardize future retirement needs.
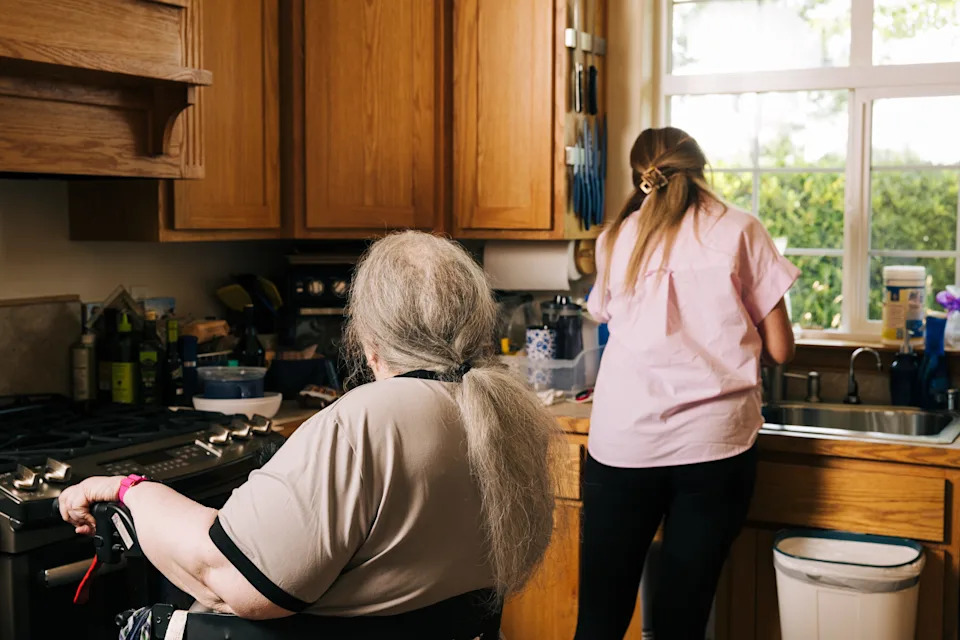
Lana Mountford pays $200 weekly for a caregiver.Chona Kasinger for BI
Hard Numbers Behind the Crisis
Long-term care prices have climbed dramatically since the late 1990s: nursing home costs are up roughly 212% and adult day services about 109% since 1997. More recently, caregiving-related prices have continued to outpace general inflation — care services rose around 17% while overall prices increased roughly 11% since 2023.
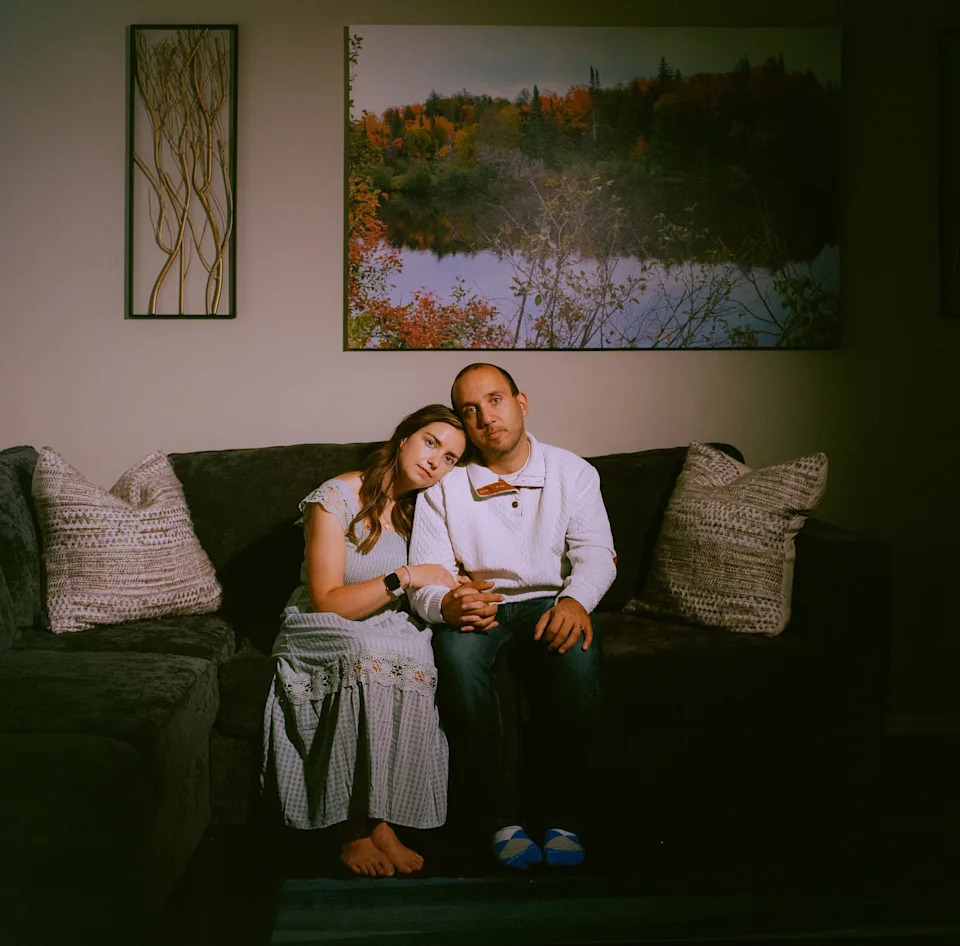
The Nuars paid six figures in out-of-pocket expenses over a few years for the care of John's father.Nic Antaya for BI
Wages for nursing and residential-care workers jumped from roughly $17 an hour to nearly $27 over the past decade — a ~57% increase from 2016 to 2026 — and those higher labor costs are often passed on to families. Private-pay home care now has a median cost near $34 per hour, and private spending on Long-Term Services and Supports (LTSS) increased 47–48% from 2019 to 2024.
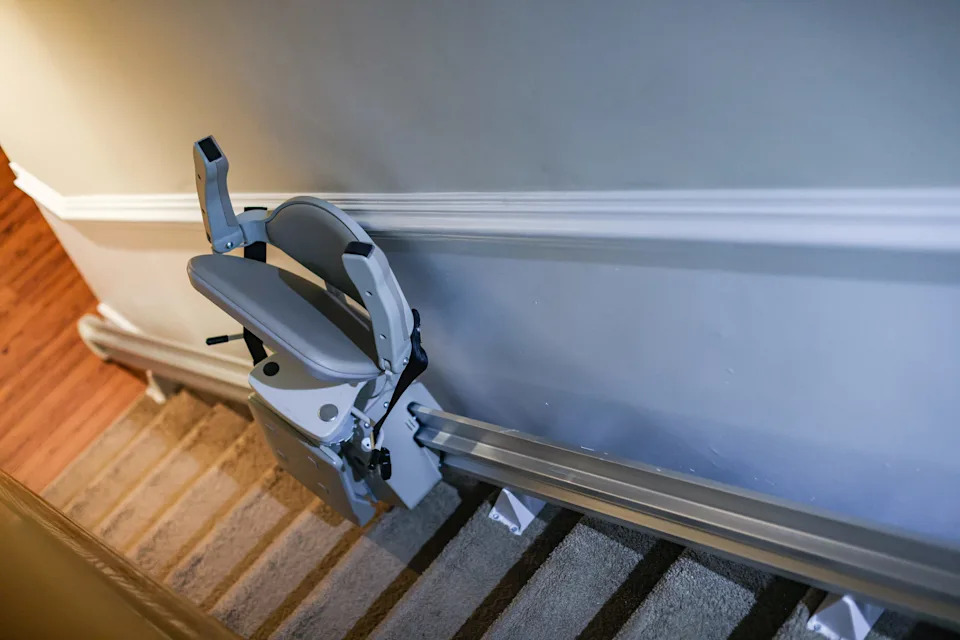
A stairlift was installed in Tamara Johnson's home after her husband suffered a stroke.Valerie Plesch for BI
Who’s Providing Care — And At What Cost?
About 59 million Americans provide care to family members or friends; roughly 48 million of them are unpaid. Home health and personal care aides earn a median hourly wage near $18 and a median annual salary around $37,200. The Bureau of Labor Statistics projects those jobs will grow about 17% from 2024 to 2034, with roughly 765,800 openings per year — indicating both rising demand and continuing workforce pressure.
“Roughly 70% of adults over 65 will need some form of long-term care during their lifetime, yet relatively few have planned financially for that possibility.” — Samir Shah, CareScout
Real Families, Real Tradeoffs
Individual experiences highlight the human cost. Lana Mountford moved into assisted living for thousands a month, later buying a home in a 55+ community in cash to control future expenses. Kathy Mullen, 64, drained her resources caring for her mother and now lives on about $25,000 a year in Social Security Disability — unsure she can ever afford her own future care. John Nuar and his wife paid roughly $120,000 out of pocket for memory-care care for Nuar’s father over three years, reflecting steep monthly increases and state-by-state eligibility differences for Medicaid.
Policy Responses and Solutions
Policymakers and advocates propose a range of responses. Options include prefunded social-insurance style programs for long-term care, stronger protections for Medicaid funding, state payroll-funded programs, and increased investment in the caregiving workforce. Examples already in motion include Washington state’s WA Cares Fund (0.58% payroll tax, lifetime inflation-adjusted cap of $36,500) and federal proposals like the Caring for Seniors Act and the bipartisan WISH Act to create a national trust fund and expand benefits.
Employers also play a role: some large companies offer caregiving navigation, legal resources, backup care, or stipends. Local governments and nonprofits can help by expanding affordable housing options for older adults — accessory dwelling units, co-housing, home modification grants, and affordable assisted-living models — which can reduce reliance on institutional care.
What Families Can Do Now
- Plan Early: Consider long-term care insurance, savings earmarked for care, and legal/financial planning.
- Explore Alternatives: Look for lower-cost housing options, community-based programs, and local supports.
- Tap Employer Benefits: Use caregiving navigation, paid leave, and backup care when available.
- Advocate: Support policies that expand workforce training, stabilize Medicaid support, and explore prefunded solutions.
The rise in long-term care costs is reshaping family decisions, career paths, and retirement security for millions. Without meaningful policy changes and investments in the caregiving workforce and affordable housing, many households will continue to face steep financial and emotional burdens.
Help us improve.