Kara Windeler sold her home in 2024 to keep paying for medical care, but says medical bills for 2025 topped $200,000 and exhausted her savings. With expanded ACA premium assistance ending Dec. 31, 2025, many Marketplace enrollees face higher premiums—KFF found average monthly net premiums rose 58% from $113 to $178 in 2026. Consumers should compare provider networks, review drug coverage, update income on Marketplace applications, and note they typically have 90 days to appeal eligibility decisions.
She Sold Her Home to Afford Care. Rising Marketplace Costs Could Force Her Off Her Plan
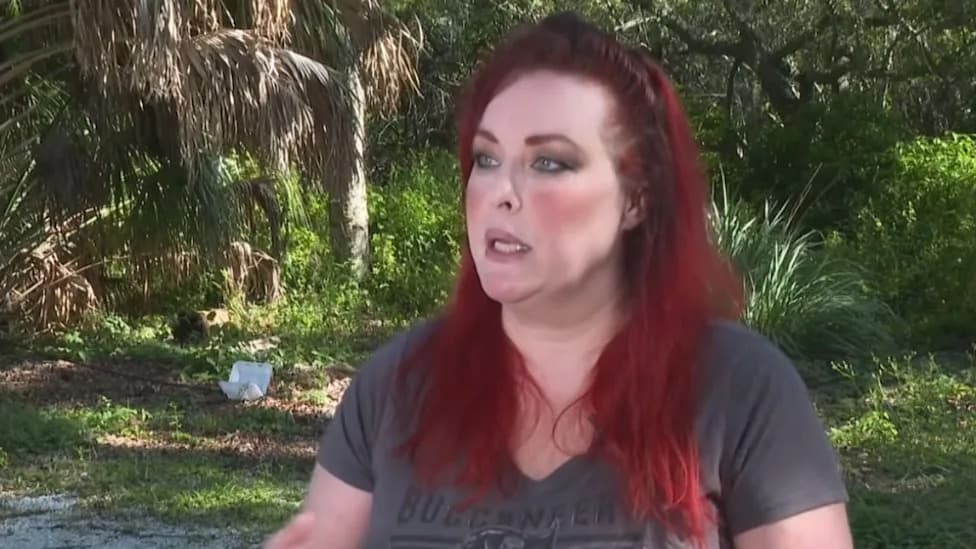
Image Credit: 10 Tampa Bay News/YouTube.
Kara Windeler has lived with chronic health problems since she was six weeks old. After selling the home she owned for 17 years in 2024 to pay medical expenses, she says the proceeds have been exhausted and insurers were billed more than $200,000 for care in 2025.
Windeler now faces a wrenching choice: keep her current Marketplace plan that provides continuity with specialists, medications and ongoing treatment—or switch in November to a substantially cheaper plan that may not cover the clinicians or drugs she relies on.
Continuity of Care Versus Lower Premiums
For patients with chronic autoimmune conditions, lower monthly premiums can come at a heavy cost. Bronze and other lower-premium plans often have smaller provider networks, higher deductibles and greater cost sharing for tests, procedures and prescriptions. Windeler warns that finding replacement specialists and treatments can mean restarting care and trying new medications that may not work on the first attempt.
"I've been liquidating little pieces of my life to pay for care," Windeler said, describing the personal toll of mounting medical bills.
Policy Changes Driving Higher Costs
The additional premium assistance available under the Affordable Care Act during recent years ended on Dec. 31, 2025. Those enhanced premium tax credits were created by the American Rescue Plan (2021) and extended through 2025 by the Inflation Reduction Act. HealthCare.gov warns that returning Marketplace customers who still qualify for savings in 2026 are likely to face higher premiums.
An analysis by KFF found that the average monthly net premium among Marketplace consumers rose 58%, from $113 in 2025 to $178 in 2026. KFF also documented a marked shift toward bronze plans, which made up 40% of Marketplace selections in 2026 versus 30% the year before. The average deductible across ACA Marketplace plans increased by $1,027, from $2,759 to $3,786—largely reflecting consumers' movement into higher-deductible plans.
What Consumers Should Do
Choosing a lower premium plan can increase total out-of-pocket spending for people with chronic conditions because network coverage, deductibles and prescription benefits vary across plans. HealthCare.gov provides tools to compare plans by doctors, facilities and prescription drugs, and links to provider directories, drug lists and each plan's Summary of Benefits and Coverage.
- Verify provider participation: Check the insurer's directory and confirm directly with medical offices before switching plans.
- Update income and household info: Marketplace premium tax credits depend on expected household income; updating your application can change eligibility and subsidy amounts.
- Know your appeal rights: If you believe the Marketplace made an error about eligibility or financial assistance, you generally have 90 days from the date of an Eligibility Notice to request an appeal.
Windeler’s situation illustrates the difficult trade-offs facing many Americans who depend on continuous specialty care: balancing monthly premiums against access to trusted clinicians, medications and potentially higher total medical costs.
Help us improve.