A Mar Vista condo owner says Liberty Mutual notified her that her policy will be canceled effective October 3 as part of the insurer's pullback from California. She had maintained the property, paid more than $1,300 annually, and now faces higher quotes or limited options amid insurers' concerns about wildfires, inflation and seismic risk. The writer urges homeowners to shop early, document communications and contact the California Department of Insurance or explore the California FAIR Plan and earthquake coverage through the CEA.
My Condo Insurer Canceled My Policy — Now I’m Scrambling to Find Coverage in Los Angeles
Last week I received an email from Liberty Mutual notifying me that my condo insurance policy will be canceled effective October 3. There was no reference to prior claims or a problem with my unit — only a broad explanation that the company is cutting exposure in California.
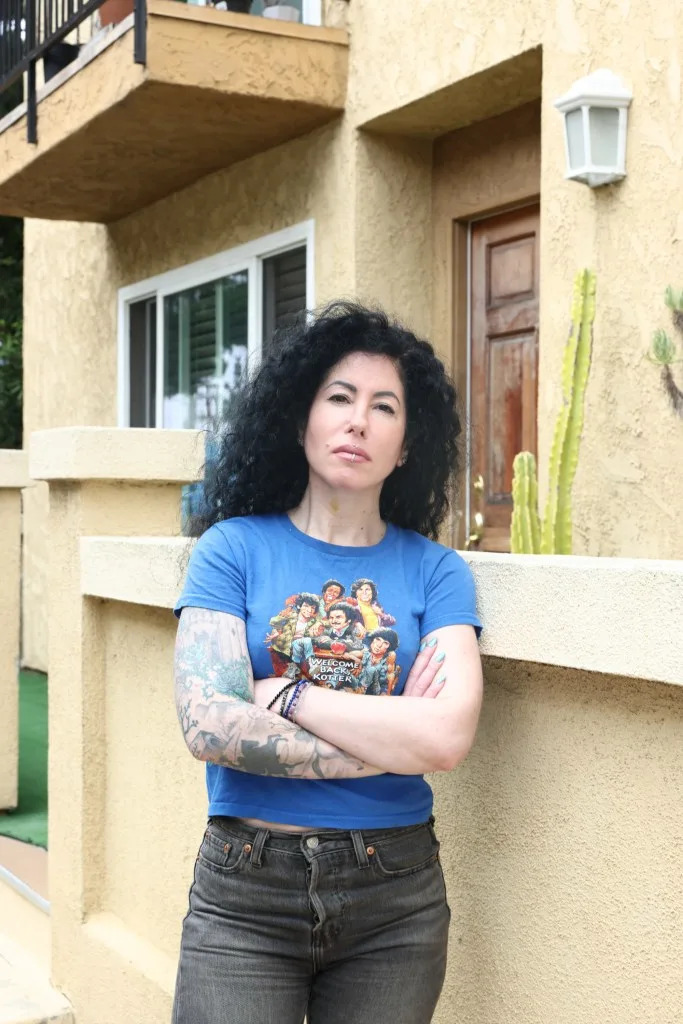
Nikki Dobrin outside her home in Mar Vista Jonathan Alcorn for CA Post
What happened
My building in Mar Vista is well maintained and has been seismically retrofitted. I bought the condo in 2016 and moved in on Halloween; I have never missed a mortgage payment or an HOA fee. I carried a policy before closing and paid more than $1,300 a year to protect my largest financial asset. Despite that, Liberty Mutual informed me the policy would not be renewed, citing marketplace volatility.
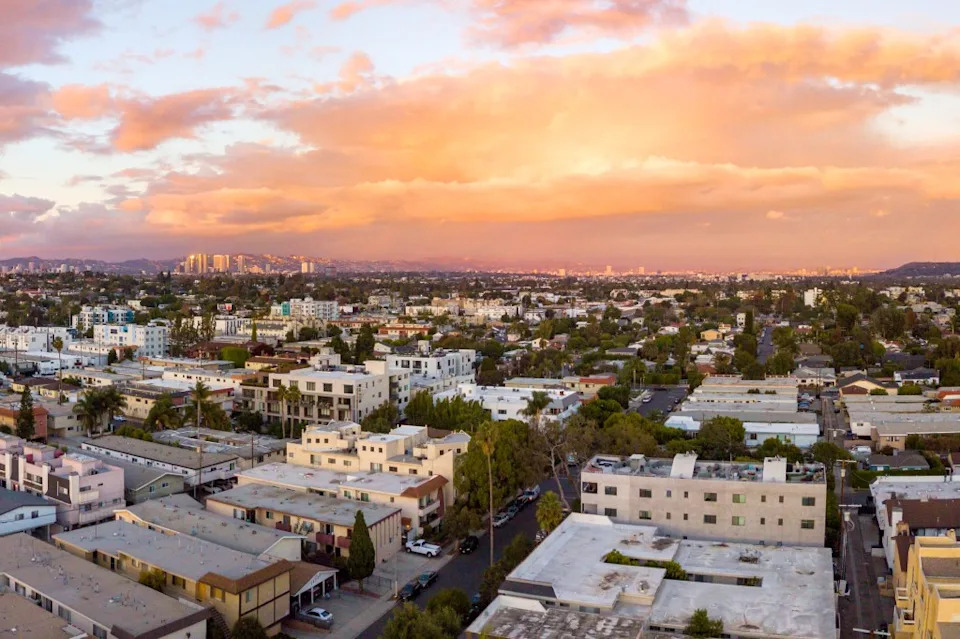
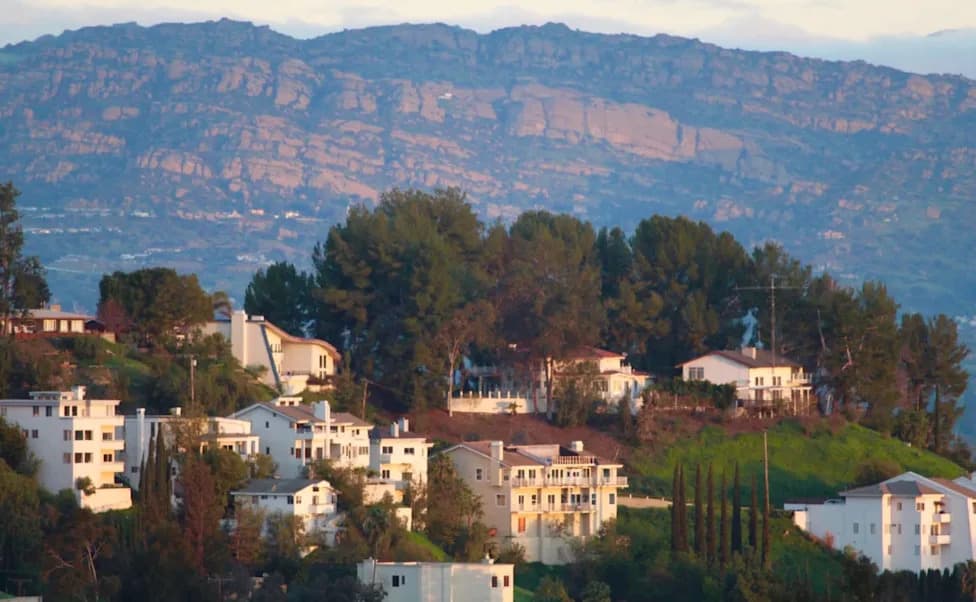
Aerial view of the Mar Vista neighborhood in Los Angeles with the Santa Monica mountains in the background Adam – stock.adobe.com
"The California insurance market has been particularly volatile, driven by factors like catastrophic weather events. Devastating wildfires have led to billions of dollars in losses for insurers," the email said, adding that inflation and rising construction costs are increasing insurer exposure.
Why it matters
Insurer withdrawals and non-renewals are occurring across Los Angeles and the state. While Mar Vista is a mostly flat, residential neighborhood and not in a high-fire zone, seismic risk remains a real concern: the US Geological Survey estimates roughly a 60% chance of a magnitude 6.7 or larger earthquake in Southern California within 30 years, and the California Earthquake Authority places the statewide chance of a 6.7+ quake at very high levels over the same period. That makes dependable insurance essential for homeowners here.
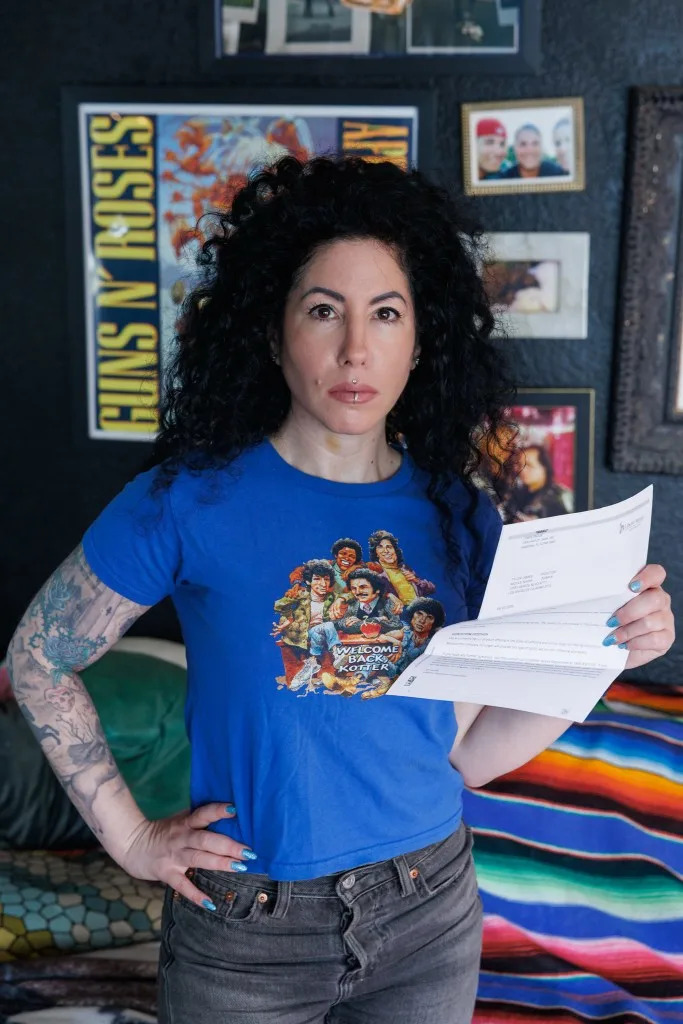
Nikki Dobrin with her letter from Liberty Mutual letting her know she was losing her insurance policy. Jonathan Alcorn for CA Post
My response and practical steps
So far I have been calling brokers and reading every policy offer carefully. Quotes I’ve seen so far are considerably higher than what I paid, and some carriers are not writing new condo policies in portions of Los Angeles. Earthquake coverage is sold separately and adds more cost.
Liberty Mutual Group is pulling back services from California monticellllo – stock.adobe.com
If your policy is non-renewed, consider these steps: call multiple independent insurance brokers, document all communications and policy paperwork, compare replacement quotes carefully, and contact the California Department of Insurance for guidance. The California FAIR Plan can be a last-resort option for property coverage, and earthquake policies are available through private insurers or the California Earthquake Authority (CEA).
Final thoughts
I understand insurers must manage risk. But when major companies retreat en masse, hardworking homeowners who have invested in this state feel abandoned. We pay taxes, keep up mortgage and HOA payments, and contribute daily to our communities — we shouldn’t have to wonder whether we can insure the biggest investment of our lives.
For now, I'm documenting everything, calling brokers, and doing everything possible to protect my home. I share this in case other Californians find themselves suddenly unprotected: start shopping early, keep records, and reach out to regulators if needed.
Nikki Dobrin is an associate digital editor at the California Post.
Help us improve.