The author reflects on moral complicity after a missile strike killed children, arguing that tax-funded defense spending can make ordinary taxpayers feel responsible. Using 2025 budget data, they estimate that individual income taxes financed about $540 billion of defense spending—roughly 20% of income-tax revenue—and show how a $200,000 earner’s share of defense could be about $7,400. The piece proposes letting taxpayers specify which controversial categories their payments may fund, keeping total liability unchanged, to register conscience and provide a clear signal to legislators.
What If You Could Pay Taxes Without Funding War Crimes? A Practical Proposal for Conscience and Policy
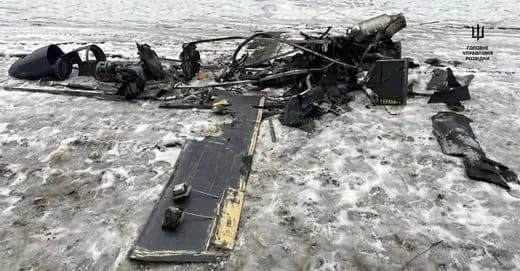
I read reports of an elementary school in Iran being struck by a missile with the same shock and horror many felt—compounded for me by a practical and moral realization: through the taxes I pay I helped finance the weapon that killed those children. Given evidence that safeguards meant to prevent such tragedies were sidelined, those deaths may amount to a war crime.
Context and the Moral Dilemma
As the philosopher Bernard Williams described in another context, I experience a kind of agent-regret when I find myself implicated, willingly or not, in a catastrophe because resources I supplied were used. Tax dollars can make individual citizens complicit in acts they find abhorrent—especially when expenditures directly violate deep conscientious commitments like opposition to particular wars, reproductive restrictions, or immigration enforcement actions.
Agent-regret: feeling responsible or implicated in a wrongdoing because one’s resources or actions contributed to it, even indirectly.
How Much Do Taxes Fund Controversial Spending?
Using 2025 U.S. budget figures: total government spending was about $7 trillion, of which $2.2 trillion was financed by borrowing (31 percent). That leaves roughly $4.8 trillion in non-borrowed spending. Payroll taxes accounted for about $1.7 trillion of that, leaving nearly $3.1 trillion financed from other revenue sources. Individual income tax receipts were roughly $2.7 trillion of that $3.1 trillion—about 87 percent of those non-payroll receipts.
Defense spending in 2025 was about $900 billion, of which approximately $621 billion was financed without borrowing. Applying the same revenue mix, individual income taxes therefore directly financed about $540 billion of defense outlays—roughly 20 percent of individual income tax revenue.
Viewed macroscopically, a single taxpayer’s contribution to defense spending is vanishingly small. But from a personal perspective, the numbers are stark. If someone earning $200,000 pays roughly $37,000 in federal taxes, then about 20 percent—approximately $7,400—of their tax bill can be attributed to defense spending. On the scale of a $3.2 million Tomahawk missile, $7,400 is roughly 0.23% of that weapon’s cost—figuratively making such a taxpayer one of about 400 people who collectively paid for the missile. The author summarizes that personal moral burden as roughly “half of a child’s death,” a deliberately stark illustration of perceived complicity.
The Proposal: Conscience Choices on Tax Forms
Is there a way to separate personal conscience from collective financing without abandoning a unified tax system? One approach is to let taxpayers specify, on their returns, how they prefer their tax dollars be allocated among certain clearly defined, controversial categories. For example, an individual could direct that none of their contributions be used for particular types of military operations they deem illegal, while allowing funds to support reproductive services or education. Another taxpayer might prioritize defense spending and exclude funding for stem-cell research. Crucially, total tax liability would remain unchanged—this system affects only allocation, not the amount owed—so there is no financial incentive to fake objections.
Why It Wouldn’t Collapse The Budget
Aggregate implementation need not derail congressional budgeting. No single taxpayer—or even most very wealthy taxpayers—represents a material share of federal receipts, so the dispersion of individual preferences is unlikely to shift total expenditures dramatically. If shortfalls appear in particular categories, roughly $840 billion in business-derived revenue (corporate income and customs) could serve as a morally neutral backstop to preserve budget stability while respecting individual designations.
Benefits Beyond Immediate Spending
Even if the reform does not immediately change programmatic outcomes, it offers two important benefits. First, aggregated preferences would produce a continuous, nationwide signal to lawmakers—an authoritative poll of fiscal conscience that could shape future appropriations. Second, it permits citizens to disavow moral responsibility for actions they find abhorrent while remaining part of a shared fiscal compact.
Objections And Responses
Critics may argue the proposal is symbolic and will not stop harm. That is true: the government would still be the actor conducting policies the public opposes. But giving taxpayers a structured way to express moral boundaries on how their dollars are used would increase democratic transparency and help channel civic pressure into legislative change without fragmenting the tax base.
Conclusion
This proposal does not pretend to prevent bombs from falling, but it does aim to restore some moral integrity to citizens who object to specific government actions. Allowing taxpayers to declare conscience-based allocations would not reduce anyone’s tax obligation or eliminate collective responsibility; it would, however, let people truthfully say, “I did what I could not to make the world worse.” That affirmation—small on its own—could, over time, influence the policies paid for by the public.
Help us improve.