Short answer: Experts say COVID-19 effects — not illegal immigration — largely explain the recent rise and fall of car insurance premiums. Driving dropped sharply during the pandemic, then rebounded with higher accident and repair costs, pushing premiums up through 2023. Insurers took rate actions and replacement costs normalized in 2024, helping premiums stabilize and fall by 2026. A limited study links uninsured-driver rates to immigration status in states that deny licenses, but that effect is too small to account for the large post-pandemic swings.
Fact Check: Experts Say COVID, Not Illegal Immigration, Drove Recent Swings In Car Insurance Premiums
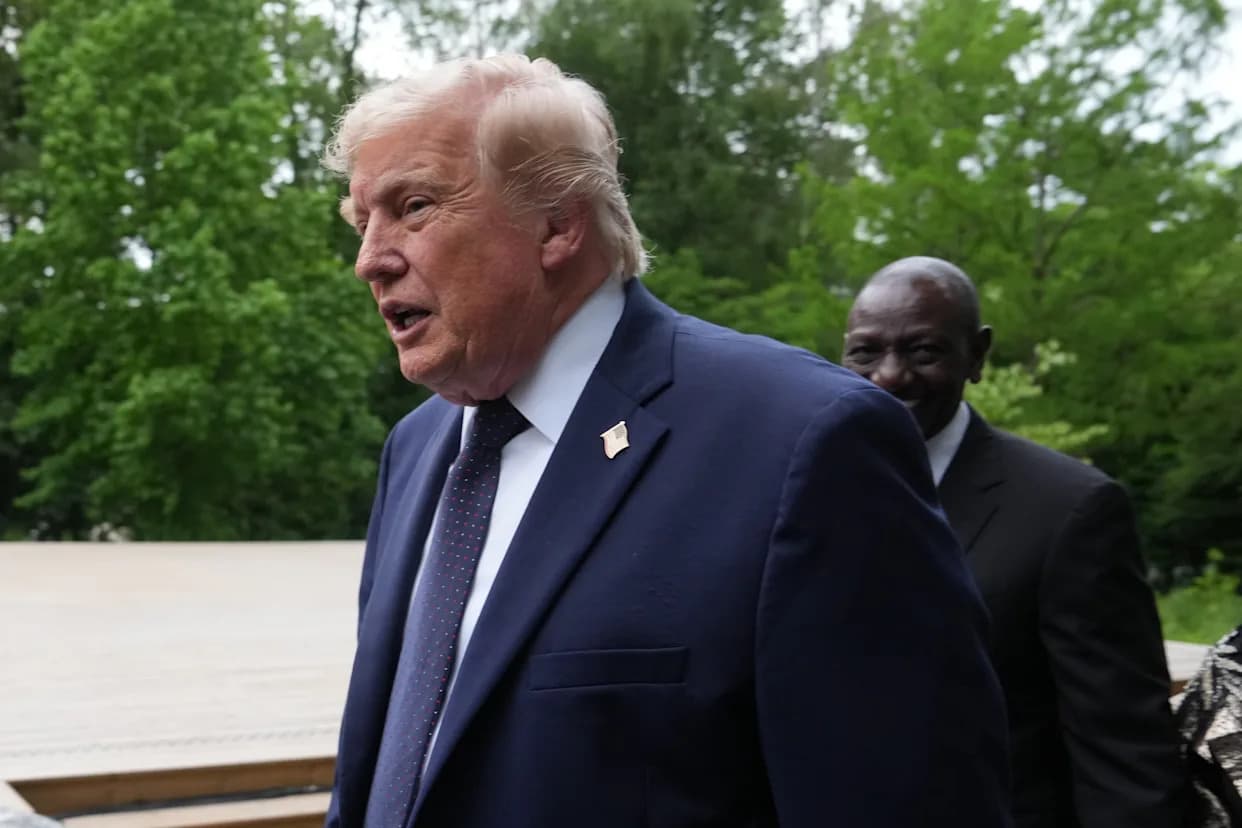
U.S. President Donald Trump walks away after a group photo of leaders at the G7 summit, Tuesday, June 16, 2026, in Evian-les-Bains, France. (AP Photo/Julia Demaree Nikhinson)(AP Photo/Julia Demaree Nikhinson)
President Donald Trump posted a graphic on Truth Social claiming his hardline immigration measures caused a recent decline in car insurance premiums and that illegal immigration under President Joe Biden produced prior increases. The image cited a Council of Economic Advisers analysis of Bureau of Labor Statistics data showing premiums rising sharply from 2021–2023, turning around in 2024, and showing negative growth so far in 2026.
What Trump Claimed
In his post, Trump wrote that “Car Insurance Premiums rose to RECORD HIGHS, forcing Law-abiding American Citizens to subsidize the ‘free riding’ Biden Illegals,” and said that “After over a year of ZERO ILLEGAL IMMIGRATION, and our highly successful efforts to REVERSE the Biden Invasion, Car Insurance Premiums have come tumbling down.”
What The Evidence Shows
The overall pattern in the chart — premiums rising through 2023 and easing thereafter — aligns with industry and government data. But experts say the primary drivers were pandemic-related effects, not illegal immigration.
When the COVID-19 pandemic began in March 2020, driving fell sharply as people stayed home and remote work expanded. That drop in miles produced fewer collisions and claims, leaving some insurers with strong profit margins for a time. As driving rebounded beginning in 2022, accidents and claims increased, influenced in part by riskier behavior such as reckless and distracted driving. At the same time, supply chain disruptions raised the cost of parts and repairs, and insurers passed those costs on to customers.
By 2024 the industry began to restore underwriting health through rate actions and other measures. As replacement costs aligned more closely with U.S. inflation and competition resumed, average premium growth moderated and in some measures turned negative by 2026.
Expert Views
“This claim is pure fiction,” said Michael Clemens, an economist at Johns Hopkins University and a senior fellow at the Peterson Institute for International Economics. He noted there is no White House, industry or academic study showing illegal immigration was the main driver of premium swings and estimated that increased undocumented migration could explain only about a 0.07% rise — far too small to account for the roughly 50% post-pandemic increase observed in some measures.
Mark Friedlander, a spokesperson for the Insurance Information Institute, said: “Over the past two years, the auto insurance industry has generated an underwriting profit following the implementation of significant rate actions to offset losses. Average auto insurance premiums have begun to stabilize, and replacement costs are more in line with the U.S. inflation rate. We are seeing average rate decreases being implemented across numerous states, as well as dividends being paid to policyholders by major auto insurers such as State Farm and USAA.”
Limited Exception: Uninsured Drivers In Some States
A 2023 study in the Journal of Insurance Issues found a narrow relationship in some areas between larger populations of people who entered the U.S. illegally and higher rates of uninsured drivers, which can raise premiums. However, that link largely appears in states that do not allow people in the country illegally to obtain driver’s licenses — a policy that typically prevents them from getting insurance in the first place. Experts emphasize this limited effect cannot explain the large, economy-wide premium swings seen after the pandemic.
Additional Context
In his post, Trump also repeated a broader and frequently debunked claim that President Biden’s policies allowed “tens of millions of criminals” into the U.S. from prisons and mental institutions — an assertion that lacks credible evidence and has been challenged by multiple fact-checkers.
The White House did not immediately respond to a request for comment.
Bottom line: While the chart Trump shared reflects real premium trends, the weight of expert analysis attributes those swings to pandemic-driven changes in driving behavior, claims frequency, and repair costs — not to illegal immigration.
Help us improve.