After being made redundant at 41, the author applied for Universal Credit and discovered that the system's taper — a 55p reduction for every £1 earned — and other rules often left them financially worse off. A tax return once wiped out a payment of £1,003.35, leaving just £321 for the month. Small, irregular earnings also made them ineligible for free prescriptions and council tax relief. They sold possessions, borrowed money and invested time in courses and volunteering. Eight months later they secured full-time work, returning with new skills but depleted savings.
Forced Onto Benefits at 41: Why Trying To Work Left Me Worse Off
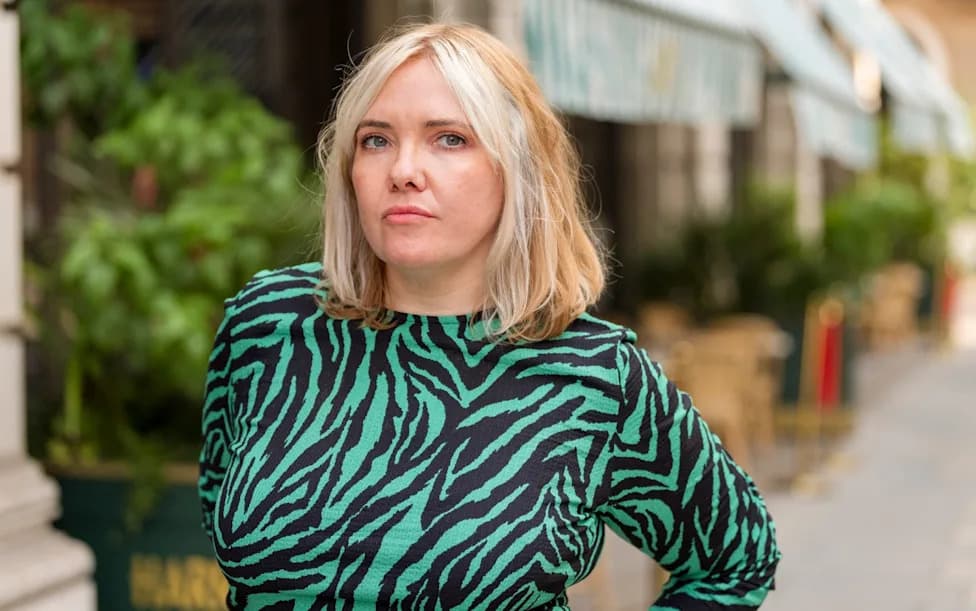
Emma Gritt learnt the hard way that trying to earn your way out of Universal Credit doesn't always pay - Andrew Crowley for The Telegraph
The notification that I had "a new journal message from Universal Credit" made my stomach drop. It was a Tuesday in March 2025, and after a morning of fruitless LinkedIn searching I learned that Universal Credit had deducted £1,003.35 from my monthly entitlement — leaving me with just £321 for the next four weeks. I scanned my flat for anything I could sell to stay afloat.
I became unemployed in November 2024 at 41. After nearly 20 years across newspapers, radio and glossy magazines, I still had marketable digital skills — from project management to launching newsletters and apps — but hundreds of applications over two months yielded nothing. With my redundancy pay dwindling, I applied for Universal Credit. The relief when I was told I was entitled to £1,325.24 a month was immediate, even though I knew it wouldn't cover everything.
How Small Earnings Made Things Worse
In January I was paid £693 for a few days' work over Christmas. When that income went through, my Universal Credit was reduced by £381. That began a six-month, Kafkaesque stretch in which trying to earn money often left me financially worse off than doing nothing. Universal Credit reduces award payments by 55p for every £1 earned. On paper that sounds reasonable, but because the work I could secure was intermittent and low-paid, accepting many of the jobs on offer would have made me worse off in practice.
Month after month my benefits were cut. Small earnings also knocked me out of other support schemes: an NHS check of HMRC records said my "monthly income" exceeded £435, so I was told I had to pay the £9.90 prescription charge. A council tax reduction was refused because I supposedly "earned too much" and had to pay the full £118 a month. And free or discounted travel is not automatic — you normally must be out of work for three months to qualify for limited discounts. Each interaction left the impression that it would be easier not to earn at all.
Jobcentre Experience And Desperation
I attended weekly Jobcentre Plus meetings and met a "job coach" who was kind but limited in what she could do for a journalist vying to get back into newsrooms. The interactions felt perfunctory: brief questions about whether I was looking for work, where I'd applied and if I'd consider other industries. In March a tax return from a previous year was treated as "earnings" and wiped out a month's Universal Credit, leaving me with £321. When I protested, I was told the money still counted as income.
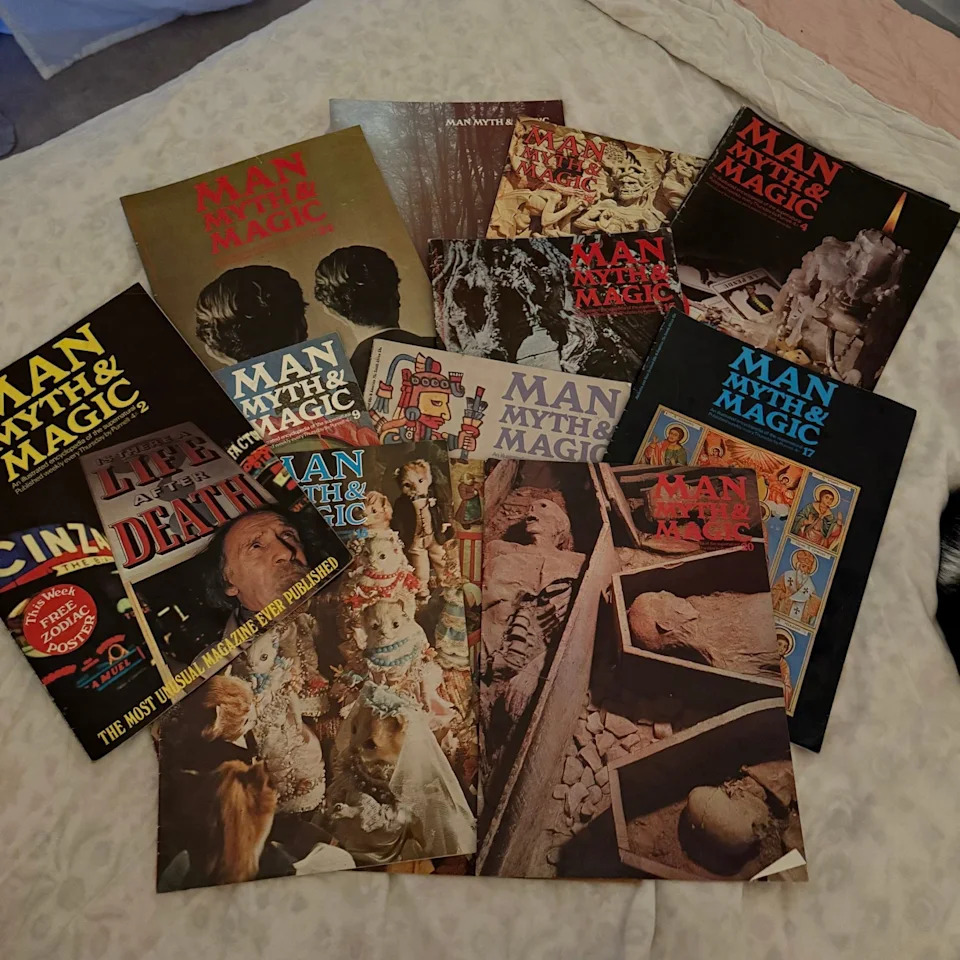
Gritt sold her old magazines, along with books, records and clothes, to help raise some money
"Look for cash-in-hand work," my job coach whispered once when I said I was close to running out of money — a suggestion I later learned was unlawful.
I saw raw distress around the Jobcentre. I watched a man break down and be escorted out after an apparent sanction left him unable to feed his children. I had no dependants, but the moment made clear that piecemeal work would not cover the costs until I found a proper full-time role.
Scraping By And Investing In Skills
To survive I sold belongings: vinyl records, clothes, books, perfume, small appliances and gadgets. I estimate I raised about £900 this way, and also borrowed from friends. My rent and bills in London were around £1,800 a month — manageable on my previous salary of £63,000 (about £3,500 take-home), but unsustainable on reduced income. Moving away felt like losing my professional network and the few journalism opportunities that remain concentrated in the capital.
Rather than sit idle, I used my unemployment to learn. I took a six-week evening course on Nietzsche, weekly art classes (one funded by the Mayor of London) and completed an A-level–equivalent in data analysis. I also volunteered with council projects, a local ecology group and the Bat Conservation Trust. The classes gave structure and, despite hating numbers, improved my CV and confidence.
Eight months after redundancy I secured full-time work. I returned to work with depleted savings but new skills and resilience — and a sharper understanding of how the benefits system can disincentivise short-term earning.
Takeaway: In the bewildering world of Universal Credit, trying to work your way out of trouble can sometimes leave you worse off; rebuilding often requires both practical sacrifices and investment in skills while navigating a system that can penalise intermittent income.
Help us improve.