The ACA marketplace is facing a deep affordability crisis after enhanced pandemic-era subsidies expired, restoring the 400% federal poverty-level cutoff and higher required contributions for many enrollees. Middle-income families have seen steep premium jumps — one Ohio family's bill rose to $2,034 monthly — and younger, healthier people are dropping coverage. That shift leaves a sicker risk pool, drives further premium increases, prompts insurer exits, and raises serious access and financial risks for people with chronic conditions.
Health-Insurance “Death Spiral”: Why ACA Premiums Are Crushing Middle-Income Families
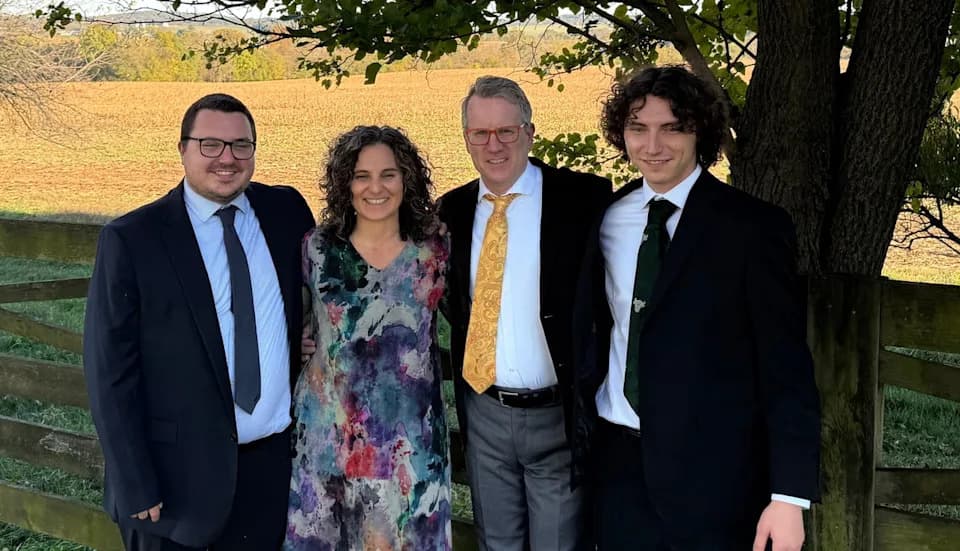
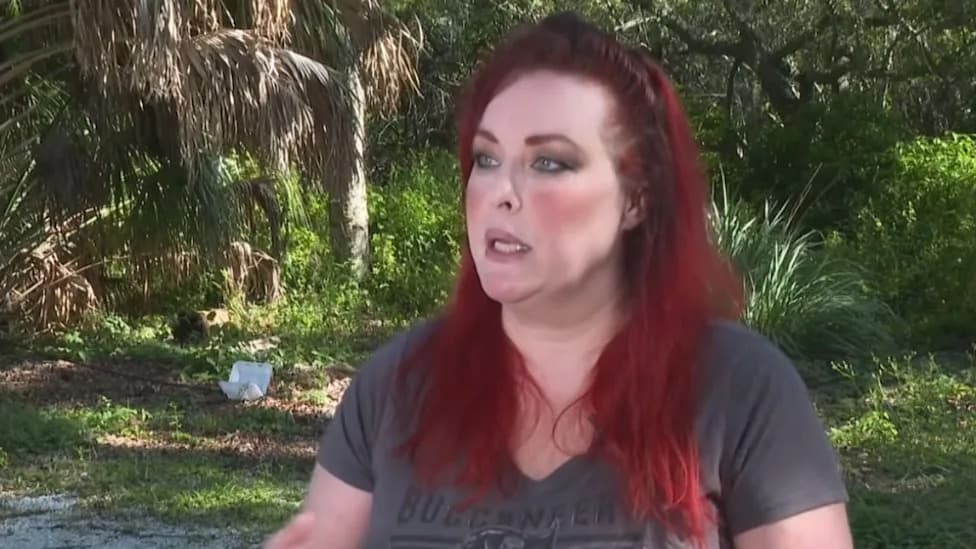
Karen Scholl with her family. (Courtesy of Karen Scholl)
Karen Scholl, a freelance writer in Ohio, has bought her family's coverage on the Affordable Care Act (ACA) marketplace for a decade. This January she watched their monthly premium climb past $2,000 for the first time: "It's now $2,034.38," she said, describing the bill for herself, her husband and their 22-year-old son, who is still in college.
The jump — a 25% increase over the prior year — follows several years of steady rises: $1,132.51 in 2023; $1,375.15 in 2024; and $1,626.30 in 2025. The increases became so extreme that their insurance broker suggested a startling workaround: if the family signed a statement saying they were Christian, they might qualify for a lower-cost healthcare-sharing ministry.
"We laughed at first," Scholl said. "We're Jewish. But when the price kept flashing in my mind, a brief thought: could we ethically do it? My grandparents escaped the Holocaust. Saying I was Christian just so I could afford healthcare made me sick and angry."
What Changed
The spike in premiums is driven by policy shifts that took place after temporary pandemic-era subsidies expired. The American Rescue Plan in 2021 eliminated the ACA's 400% federal poverty level cutoff and reduced required premium contributions, making subsidies available to many who had not previously qualified. The Inflation Reduction Act extended that relief through 2025.
Because Congress did not renew the enhanced assistance, 2026 largely reverted to the ACA's original premium-tax-credit formula. In most cases the 400% cutoff returned, and many enrollees — especially middle-income households that had benefited temporarily — lost aid or now face higher required contributions before subsidies apply.
How This Triggers A “Death Spiral”
The result is concentrated sticker shock at both ends of the income scale. As premiums rise, younger and healthier people are most likely to drop coverage because they judge the cost as not worth the benefit. Of the 1.2 million people who left marketplace coverage between 2025 and 2026, almost half were aged 18 to 34.
"When the healthier customers drop and sicker, older enrollees remain, insurers face a more expensive pool. That pushes premiums higher still or convinces insurers the market isn't profitable," explained health policy analyst Louise Norris.
Insurers then face two options: raise premiums further to cover rising costs or exit the market. At least a dozen insurers have announced plans to leave the ACA marketplace after 2026. CVS Health's Aetna withdrew from individual exchanges at the end of 2025, affecting roughly one million enrollees across 17 states. Cigna plans to exit after 2026, affecting nearly 400,000 people.
Real-World Consequences
The effects reach beyond premiums. Jennifer Noonan, vice president of clinical strategy at nonprofit Accessia Health, said her organization is seeing more and earlier requests for help from people with rare and chronic conditions. As people downgrade plans or drop coverage, out-of-pocket costs for specialist visits, labs and ongoing treatments climb — and missed screenings or paused therapies can become preventable complications later on.
For the Scholls, dropping coverage is not a practical option: Karen's husband Mark has asthma and needs regular medications. Even with insurance, those prescriptions can be costly; copays for doctor visits run about $50, which feels especially painful alongside a $2,034 monthly premium. Their older son recently found employer coverage, but their younger son remains a student at Ohio State and would be difficult to remove from the family plan without significant trade-offs.
What Comes Next
Analysts warn that unless policy action intervenes, parts of the ACA marketplace could increasingly resemble a two-tier system: middle-income families technically insured but functionally underinsured, while risk pools become more concentrated and costly. That dynamic makes coverage less affordable and less reliable for many Americans.
Karen Scholl with her family. (Courtesy of Karen Scholl)
Help us improve.