Bottom line: The D.C. Circuit affirmed a preliminary injunction, finding the IRS violated laws protecting tax return confidentiality by using a flawed "Data‑Exchange Procedure" to disclose 47,289 records to ICE. The court called the procedure legally insufficient because it required only superficial address digits—not verified addresses—and said any policy complaints belong to Congress, not the courts. The panel also dismissed the IRS's procedural objections as "weak sauce."
Appeals Court: IRS Illegally Shared 47,289 Tax Records With ICE — 'Take Your Gripe To Congress'
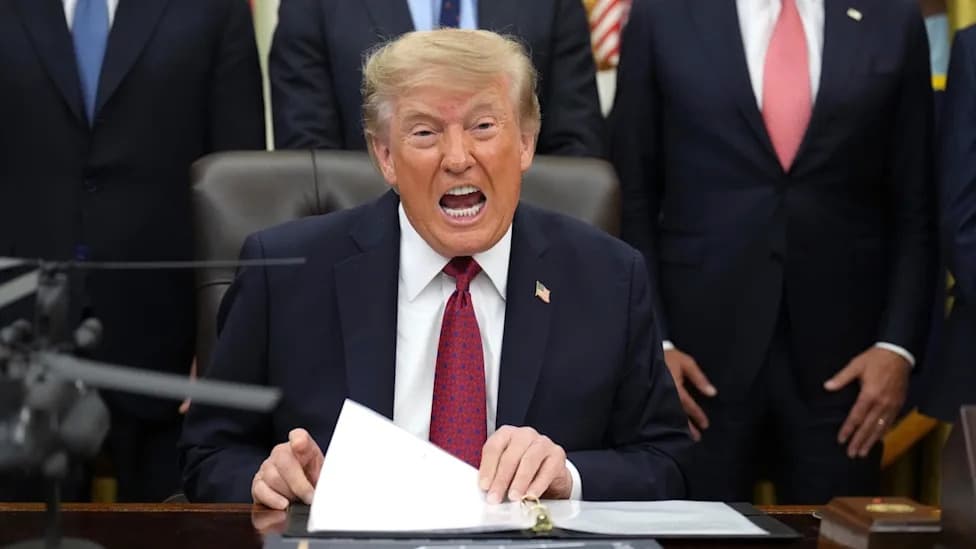
President Donald Trump speaks outside the Oval Office of the White House, Monday, April 13, 2026, in Washington (AP Photo/Alex Brandon).
A federal appeals court on Tuesday affirmed a lower‑court injunction, ruling that the Trump administration and the IRS violated statutory protections when the agency disclosed confidential tax return information to Immigration and Customs Enforcement (ICE).
The challenge was brought in February 2025 by the nonprofit Center for Taxpayer Rights and two unions, who sued over a broader data‑sharing arrangement tied to the Department of Government Efficiency's (DOGE) campaign to access agency systems and reorganize parts of the federal government. Although the administration has largely stopped embedding DOGE staff within agencies, litigation over these changes continues.
U.S. District Judge Colleen Kollar‑Kotelly previously paused the data‑sharing arrangement between ICE and DOGE (which included the IRS) in November 2025. The government appealed that preliminary injunction to the U.S. Court of Appeals for the D.C. Circuit while the district court continued to address the merits.
Appellate Ruling Affirms Statutory Protections
A three‑judge panel — led by Circuit Judge Cornelia Pillard and joined by Judges Patricia Millett and Robert Wilkins — emphatically affirmed the lower court in a 32‑page opinion. The opinion opens by invoking the "Watergate scandal" to underscore long‑standing concerns about misuse of taxpayer information for political or punitive purposes.
The court concluded the IRS violated the statute that bars disclosure of tax return information to other federal agencies unless strict conditions are met. The D.C. Circuit found the IRS failed to ensure ICE's requests met those statutory requirements before disclosing records.
"The procedure failed to ensure that ICE's requests complied with statutory requirements. The IRS nonetheless began using the procedure to disclose tens of thousands of records."
Flawed 'Data‑Exchange Procedure'
The opinion examined an IRS process dubbed the Data‑Exchange Procedure, which the IRS implemented after ICE expressed interest in return information for more than a million individuals. Under that procedure the IRS required only that ICE supply five or nine digits in an address field to trigger disclosure. Those digits need not be a valid ZIP code, nor must ICE provide a street name, city, or state.
Using that lax verification method, the IRS identified and disclosed 47,289 tax records to ICE without confirming whether the requests actually contained information plausibly reflecting "the name and address of the taxpayer." The appeals court characterized defenses of the procedure as "a nonstarter," concluding the procedure likely caused statutory violations and would continue to do so if left in place.
The court also highlighted that the IRS itself has acknowledged that immigration enforcement is not an authorized purpose for redisclosing returns or return information, and that Congress has imposed civil and criminal penalties for willful improper disclosure.
Government Arguments Rejected
The government argued the injunction hampered criminal investigations and complained about aspects of how the district court fashioned the injunction. The D.C. Circuit was unpersuaded. The panel said those complaints were "a gripe with Congress, not the court," and called the IRS's objection to the injunction's form "weak sauce," noting the district court permitted filings under seal to protect legitimate investigative material.
For now, the appellate ruling leaves the preliminary injunction in place and underscores that agencies must follow statutory safeguards when sharing sensitive taxpayer information with other federal entities.
Key actors: Center for Taxpayer Rights and two unions (plaintiffs); Department of Government Efficiency (DOGE); ICE; IRS; U.S. District Judge Colleen Kollar‑Kotelly; D.C. Circuit Judges Cornelia Pillard, Patricia Millett, and Robert Wilkins.
Help us improve.